Struggling With Medical Bills? Here’s 5 Things You Can Do
Mounting medical bills can quickly drain the bank accounts of everyday households and place enormous emotional strain on individuals who are actively recovering from serious health issues. Health care expenses consistently climb each year at rates that outstrip normal household earnings, leaving even cautious savers vulnerable when unexpected surgeries, complex diagnoses, or emergency admissions take place. These sudden medical events are almost immediately followed by a wave of complex statements, collection letters, and urgent demands for payment.
Carrying thousands of dollars in health care debt can feel overwhelming, but medical balances behave very differently from traditional retail obligations or consumer loans. Hospitals, physician practices, and medical billing offices operate under strict legal frameworks, regulatory mandates, and financial policies. Because patient finance departments face unique administrative hurdles and institutional incentives, patients hold substantial leverage to review, dispute, negotiate, and reduce their balances.
Key takeaways
- Upwards of 80 percent of all hospital statements contain billing mistakes, unrendered treatments, or duplicate line items.
- A 2021 study revealed that 93 percent of patients who actively negotiated their medical bills succeeded in lowering or eliminating their balances.
- The Affordable Care Act legally obligates non-profit hospitals to maintain financial assistance policies and provide fee reductions for qualifying low-income individuals.
- Shifting health care obligations to high-interest credit cards or home equity loans can introduce severe financial hazards, including potential home foreclosure.
How Medical Billing Functions Behind the Scenes
To successfully challenge an inflated medical account, you need to understand how clinical activity transforms into a final financial balance. Patients often assume that because medical providers deliver sophisticated clinical care, their administrative offices run with equal precision. While clinical teams prioritize patient vitals, medication administration, and surgical procedures, the back-office billing machinery operates in an entirely different environment characterized by high volume, manual entries, and fragmented electronic systems.
Every single interaction during a hospital stay requires cross-system documentation. When a nurse dispenses an oral tablet, an orderly opens a sterile supply tray, or an imaging technician performs a scan, those events are supposed to be entered into an electronic health record. Those clinical notes are subsequently translated by medical coders into specialized alphanumeric procedure and diagnostic codes before generating an official charge. Because this workflow relies on repeated data handoffs across multiple shifts and departments, errors happen with remarkable frequency.
One of the most persistent billing pitfalls is the appearance of duplicate charges. For example, when a patient is moved from an emergency department to an intensive care unit, both units might log separate fees for the same routine blood panel or intake scan. Shift handoffs among nursing personnel can also trigger double billing for daily medication doses. Furthermore, procedures that were scheduled but later canceled or replaced with alternative therapies frequently remain on the final itemized printout, artificially inflating your total balance.
Five Key Strategies to Resolve Health Care Debt
Resolving burdensome medical debt does not require a single miraculous fix. Instead, it relies on applying structured financial strategies that methodically chip away at false charges, legal reductions, and realistic settlement options.
Check the Medical Bills for Accuracy
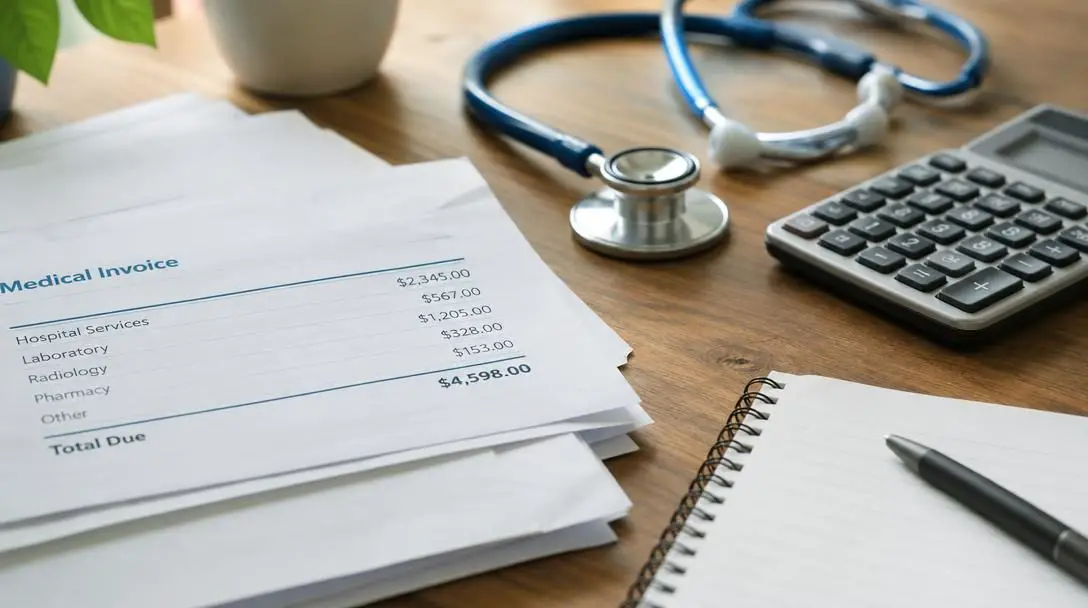
The standard summary bill sent through the mail rarely reveals the actual services for which you are being charged. Paying a balance based solely on a high-level statement often means paying for clerical mistakes, unrendered treatments, or inflated room fees. Your first line of defense is securing a fully itemized statement that details each specific service, consumable product, and medication code.
Once the itemized record arrives, examine every line item against your personal recollection and discharge paperwork. Cross-check dates of service, look for duplicate lab entries recorded on the same day, and verify that specialized diagnostic imaging matches what was discussed with your care team. Bringing verified inaccuracies directly to the billing department forces an administrative review that often substantially reduces the gross total.
Leverage Legally Required Reductions
Health care debt holds a unique regulatory status compared to commercial debt. Under provisions established by the Affordable Care Act, all non-profit hospitals are legally required to maintain written financial assistance policies—often known as charity care guidelines. These federal standards ensure that eligible low-income patients receive full waivers or marked fee reductions based on family income thresholds.
Non-profit hospitals publish these eligibility policies online and make paper applications available upon request. These guidelines specify income brackets, household size allowances, and documentation standards. If your current household income falls within the facility's designated sliding scale, submitting an application can legally mandate the facility to discount your charges or wipe them out entirely.
Negotiate a Reasonable Payment Schedule or Reduction
Direct communication with patient accounting teams consistently produces meaningful savings. A landmark 2021 study revealed that 93 percent of individuals who negotiated with their health care providers had their bill reduced or completely eliminated. Billing managers operate with the understanding that pursuing full charges through third-party collection agencies yields low returns, and an individual pushed into bankruptcy can erase medical debts entirely in court, leaving the provider with zero.
When health care providers realize an unpaid account risks total discharge in bankruptcy, establishing a realistic payment plan or discount becomes their best financial option.
Because providers want to avoid complete debt abandonment, patient finance representatives are routinely authorized to structure manageable installment agreements. An affordable payment plan divides your adjusted balance into predictable, interest-free monthly payments spread over an agreed-upon timeframe, safeguarding your day-to-day budget while keeping the account out of aggressive collection channels.
Use Borrowing Resources Wisely
Patients recovering from health crises face heavy emotional stress when collection calls and urgent payment notices arrive. Debt collectors frequently attempt to capitalize on this anxiety by encouraging individuals to put their medical balances on a consumer credit card. However, converting zero-interest health care debt into credit card debt replaces a negotiable balance with an aggressive, compounding obligation subject to exorbitant interest charges.
Homeowners often explore home equity loans or lines of credit to pay off outstanding medical accounts. Because home equity loans are secured by the underlying real estate, lenders generally offer lower interest rates than unsecured consumer loans. However, using this mechanism creates a second mortgage. Defaulting on a home equity loan puts your primary residence at direct risk of foreclosure, transforming a medical bill dispute into a potential housing emergency.
Consider Accepting a Helping Hand
Overcoming serious health-related expenses often requires tapping outside support systems. Numerous non-profit organizations, disease-specific foundations, and regional charitable entities maintain dedicated grant funds designed to assist patients struggling with specialized treatment costs, living expenses, or outstanding therapy bills.
In addition to organized charitable foundations, digital platforms like GoFundMe have transformed the way individuals manage catastrophic medical expenses. Many families facing extensive out-of-pocket costs find meaningful financial relief by sharing their story publicly. Accepting community generosity allows friends, neighbors, and sympathetic donors to ease your financial recovery, providing vital capital without incurring further debt.
At a Glance: Medical Debt Relief Options
Choosing the correct financial pathway depends heavily on your household income, the classification of the medical facility, and your overall risk tolerance. Review the trade-offs of each major debt-reduction strategy below:
| Resolution Strategy | Primary Advantage | Key Risk or Drawback | Ideal Candidate |
|---|---|---|---|
| Itemized Bill Audit | Eliminates unrendered care and duplicate fees | Demands time and meticulous line-by-line review | Anyone receiving an initial high-balance hospital bill |
| Charity Care Application | Can erase up to 100 percent of the outstanding debt | Restricted to non-profit hospitals and income tiers | Low-to-moderate-income households facing large balances |
| Direct Negotiation | High statistical success rate for balance reductions | Requires persistence and direct communication | Patients with stable income needing manageable terms |
| Home Equity Borrowing | Provides lower interest rates than credit cards | Establishes a second mortgage and risks foreclosure | Homeowners with substantial equity and secure income |
| Community Crowdfunding | Brings in non-repayable community funding | Requires sharing personal health details publicly | Patients facing catastrophic, ongoing treatment expenses |
Step-by-Step Guide: How to Audit and Dispute Your Medical Bills
Resolving complicated balances requires a calm, sequential workflow. Taking organized administrative steps protects your rights and creates an audit trail that works to your advantage throughout the dispute process.
- Request an itemized statement: Contact the billing office directly and ask for a complete, itemized breakdown containing all billing codes, descriptions, and unit prices. Refuse to pay based on summary statements.
- Audit every single line item: Compare the itemized sheet against your calendar, prescriptions received, and physician notes. Highlight duplicate medication orders, room charges entered for days after discharge, or scans that were scheduled but ultimately canceled.
- Examine non-profit assistance policies: If your treatment took place at a non-profit facility, locate their financial assistance program documents online to review their income requirements under the Affordable Care Act.
- Open direct discussions with billing representatives: Call the patient accounts department with your notes in hand. Dispute erroneous charges directly, present documentation of financial hardship if applicable, and propose an interest-free monthly installment plan.
- Explore community and crowdfunding support: If a balance remains after audits and charity care adjustments, submit applications to regional patient assistance charities or set up a crowdfunding page to share your recovery journey.
Costly Mistakes to Avoid When Managing Health Care Balances
When collection letters arrive, fear and urgency can cloud financial judgment. Steering clear of common mistakes will keep your balance negotiable and protect your broader financial stability:
- Paying immediately out of panic: Sending payment immediately upon receiving a first summary notice forfeits your ability to challenge incorrect codes, inflated supply costs, and duplicate charges.
- Transferring medical debt to credit cards: Shifting an account to an unsecured credit card converts flexible medical debt into rigid commercial debt that incurs high interest and limits your negotiation leverage.
- Risking home security thoughtlessly: Taking out a home equity loan introduces a second mortgage on your primary property, exposing your home to foreclosure if future complications disrupt your income.
- Assuming published charges are fixed: Believing hospital fees are unchangeable leads many patients to overpay, ignoring the proven fact that 93 percent of negotiated accounts result in reduced balances.
- Letting personal pride block financial aid: Reluctance to request charity care discounts or launch a public fundraising effort leaves valuable community resources untapped when support is readily available.
Frequently asked questions
Why do hospital bills contain so many errors?
Hospital billing requires extensive data entry by nurses, technicians, and doctors across multiple computer systems and departmental transfers. Because medical teams prioritize critical care over clerical coding, documentation resets between shift changes and overlapping orders frequently produce duplicate charges, unrendered supply fees, and incorrect procedure codes.
How does the Affordable Care Act help with medical debt?
The Affordable Care Act mandates that non-profit hospitals maintain clearly defined financial assistance and charity care policies. These institutions are legally obligated to publish income qualification guidelines and offer service reductions or total balance waivers to qualifying low-income patients.
Can medical providers refuse to negotiate payment plans?
While providers can set their own terms, patient accounting departments are almost always open to payment agreements. Providers know that aggressive collections carry high administrative costs and that patients facing unmanageable debt may file for bankruptcy, which leaves the hospital with zero compensation.
Is it ever smart to pay medical bills with a home equity loan?
A home equity loan carries substantially lower interest rates than consumer credit cards because it is secured by property. However, it functions as a second mortgage and introduces significant risk: if you default on payments due to illness or job loss, you risk losing your home through foreclosure.
What should I do if a representative offers a quick discount for immediate payment?
Prompt-pay discounts can be beneficial, but you should never accept one before reviewing an itemized statement. Ensure all duplicate entries and unrendered services are removed first, and check whether you qualify for larger reductions under charity care guidelines before agreeing to settle.
The Bottom Line
Dismantling a burdensome health care balance is a methodical process that requires patience, organization, and a clear understanding of patient rights. Medical billing statements are not ironclad decrees; they are administrative summaries generated by fallible record systems. By maintaining detailed notes of every phone call, verifying every line item on an itemized bill, and asserting your eligibility under institutional charity care programs, you can take control of your financial recovery.
Always secure written documentation of any settlement, rate reduction, or installment schedule agreed upon with patient accounts representatives. Protect your long-term assets by avoiding high-interest consumer credit cards and unnecessary home equity borrowing. With deliberate auditing, proactive negotiation, and the support of community programs, you can eliminate unfair charges and restore your peace of mind.