Take-Home Pay Made Easy: How to Calculate Your Salary
When you evaluate a new job offer or negotiate a well-deserved raise, the compensation under discussion is almost always presented as a single headline number: an annual salary or a standard hourly wage. While this headline figure represents the total earnings agreed upon by you and your employer, it rarely matches the actual sum deposited into your checking account on payday. The gap between what you earn on paper and the actual cash available for daily spending can be substantial, often catching even seasoned workers off guard.
Knowing your gross compensation is important for your career trajectory, but understanding your take-home pay—frequently referred to as net pay—is the true foundation of personal financial stability. Calculating your net pay requires navigating a series of mandatory and voluntary withholdings that modern payroll administrators process every pay period. Taking the time to master this calculation removes the mystery from your paycheck, giving you direct control over your personal cash flow and financial future.
Key takeaways
- Take-home pay, or net pay, is the actual dollar amount remaining after gross earnings are reduced by pre-tax deductions, statutory taxes, and post-tax withholdings.
- Pre-tax deductions for health insurance, retirement savings, and flexible spending accounts directly lower your taxable baseline, producing meaningful tax savings.
- Post-tax deductions, such as wage garnishments and child support payments, are subtracted only after mandatory taxes are calculated and do not lower taxable wages.
- Accurately converting your compensation requires identifying the correct pay schedule, dividing annual salary by 26 for bi-weekly pay or 52 for weekly pay.
- Prioritizing non-negotiable living essentials like housing, utilities, and food before funding lifestyle splurges protects household finances from unexpected cash crunches.
Understanding the Architecture of a Modern Paycheck
A paycheck is rarely a straightforward exchange of hours for a single lump-sum deposit. Instead, modern compensation operates through a structured accounting pipeline governed by federal tax laws, state and local regulations, and your own personal benefit selections. Each phase of this pipeline systematically adjusts your gross earnings down to your final net pay.
The payroll process begins with gross earnings, which serve as the baseline for every calculation that follows. From that starting number, specific payroll items are subtracted in a precise order of operations. Bypassing or misinterpreting the order of these deductions is the primary reason individuals miscalculate their real purchasing power.
Understanding the difference between what you earn on paper and the cash deposited into your bank account provides total clarity and control over your daily financial life.
The first reductions applied are pre-tax deductions. Because these amounts are removed directly from your gross earnings prior to tax assessment, they reduce your taxable wage base. Next, statutory taxes are determined and withheld according to government withholding tables, personal filing status, and income thresholds. Finally, post-tax deductions are pulled from whatever balance remains. Only after each layer is properly subtracted do you reach your net take-home pay.
Comparing Deductions: Pre-Tax vs. Post-Tax
To calculate take-home pay accurately, you must distinguish between deductions that reduce your tax burden and those that are processed after taxes have already been calculated. Misclassifying these withholdings leads to distorted net income projections and unexpected shortfalls.
| Deduction Category | Effect on Taxable Income | Timing in Pay Sequence | Common Workplace Examples |
|---|---|---|---|
| Pre-Tax Deductions | Reduces taxable earnings baseline | Subtracted from gross earnings before tax calculations | Health insurance premiums, retirement plan contributions, flexible spending accounts (FSAs) |
| Statutory Tax Withholdings | Calculated from adjusted taxable baseline | Withheld after pre-tax deductions are cleared | Federal income tax, state income tax, local taxes |
| Post-Tax Deductions | No impact on taxable income | Subtracted after all taxes have been computed | Child support obligations, court-ordered wage garnishments |
A Step-by-Step Walkthrough to Determine Your Take-Home Pay
Determining your net pay does not require accounting certification or specialized software. By approaching the calculation as an orderly, multi-stage formula, any salaried or hourly employee can project their take-home earnings with confidence.
- Determine your gross pay: Gross pay represents everything you earn in a pay period before any subtractions take place. For salaried professionals, calculate your per-period gross by dividing your annual salary by the total number of pay cycles per year (typically 26 periods for bi-weekly pay schedules or 52 periods for weekly pay schedules). If you work on an hourly basis, multiply your agreed hourly wage by the specific hours worked during that pay cycle, making sure to include any overtime compensation, commissions, or special bonuses earned during that timeframe.
- Calculate your pre-tax deductions: Identify all voluntary and mandatory benefit programs withheld prior to taxation. Add up the per-paycheck costs of your employer-sponsored health insurance premiums, contributions toward your retirement savings account, and allocations to a flexible spending account (FSA). Subtract this combined figure from your gross pay to establish your adjusted taxable baseline.
- Subtract your tax withholdings: Tax liabilities depend upon your overall income level and personal tax filing status. Because withholding tables and rates differ across jurisdictions and filing brackets, consult the official IRS tax withholding calculator or work with a qualified tax professional to identify your per-check tax withholding obligations. Subtract these statutory taxes from your taxable baseline to see what remains.
- Factor in post-tax deductions: Review your pay summary for any obligations that must be settled after taxes are drawn. These post-tax items include legal obligations such as child support payments or mandatory wage garnishments. Subtract these liabilities directly from your after-tax balance.
- Apply your take-home pay to your household budget: The remaining figure is your true net pay. This is the exact amount deposited into your account, ready to be divided among your fixed living costs, future savings reserves, and discretionary lifestyle spending.
Workplace Scenarios: Why Take-Home Pay Varies Across Workers
Because paychecks reflect individual life choices and employment structures, two coworkers sitting side by side with identical job titles can take home substantially different net compensation. Examining distinct workplace arrangements demonstrates how payroll mechanics work under different conditions.
Salaried vs. Hourly Earnings Models
The primary baseline for gross pay calculations hinges on whether an employee is compensated via a fixed salary or an hourly wage. A salaried worker operating under an annual employment agreement enjoys predictable per-period gross compensation. When paid on a bi-weekly cycle across 26 pay periods, their gross pay remains identical from check to check unless an extraordinary bonus or commission is awarded.
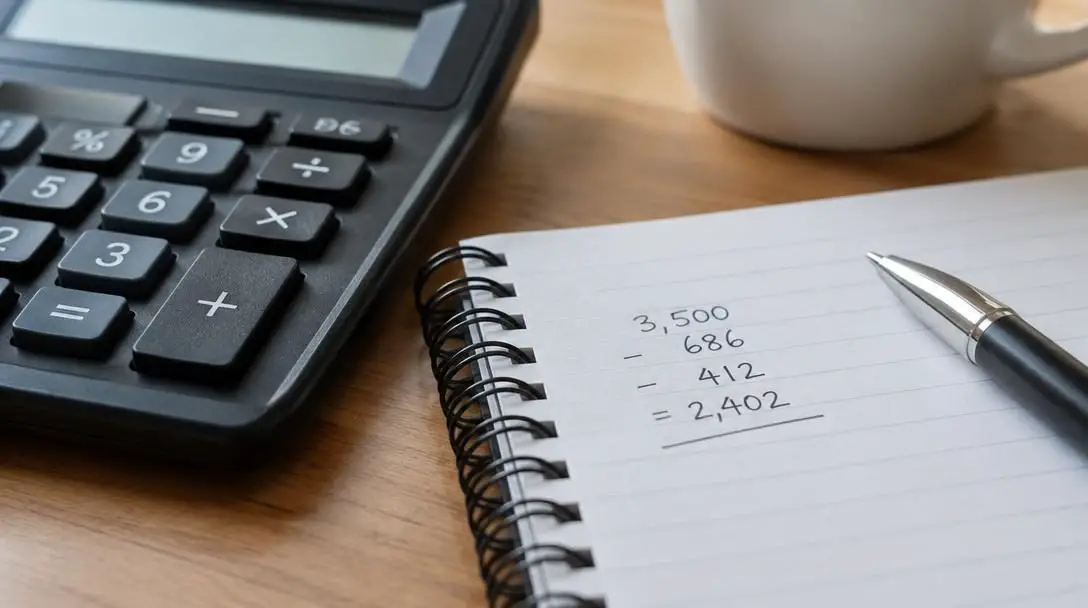
In contrast, an hourly employee experiences natural fluctuations in take-home pay. Their baseline calculation must be performed afresh at the end of each cycle by multiplying logged hours by the established wage. When business demand requires extra shifts, overtime pay must be factored into that specific cycle's gross earnings, altering both taxable wages and the final deposit amount.
Varied Benefit Elections and Pre-Tax Choices
Voluntary pre-tax selections introduce a secondary layer of variation. Consider two colleagues who both earn an identical gross salary. The first worker elects comprehensive health insurance coverage through the company, contributes a consistent portion of earnings into an employer-sponsored retirement savings account, and puts funds into a flexible spending account for expected healthcare costs. These deductions reduce that worker's taxable baseline significantly.
The second coworker might obtain medical coverage through an outside source, opt out of workplace retirement plans, and decline all flexible spending elections. Although the second employee receives a larger immediate paycheck because fewer deductions are removed, they forgo the significant tax savings and long-term security generated by the first employee's pre-tax withholdings.
Divergent Tax Filing Statuses
Even when two employees record the exact same gross earnings and maintain identical pre-tax benefit packages, their final take-home pay can still differ dramatically because of income tax withholding rules. Government withholding formulas factor in an employee's selected tax filing status.
A worker using one filing status may face a higher withholding baseline than a colleague claiming a different status with distinct allowances or family adjustments. Because statutory withholding formulas correspond directly to individual household profiles, tools like the IRS tax withholding calculator are critical for tailoring your paycheck to your exact household circumstances.
Common Payroll Pitfalls and Mistakes to Avoid
Because calculating take-home pay involves several interdependent steps, minor oversights can lead to major budget discrepancies. Staying alert to frequent payroll missteps ensures your spending projections stay grounded in real numbers.
Confusing Gross Earnings with Net Pay
The most pervasive error among professionals entering the workforce or starting a new role is building lifestyle commitments around gross compensation. Signing an expensive residential lease or financing a vehicle based on headline earnings leaves you financially vulnerable once pre-tax benefits, statutory withholdings, and deductions are removed from your check.
Misidentifying Pre-Tax and Post-Tax Deductions
Pre-tax deductions—including retirement contributions, healthcare insurance premiums, and flexible spending accounts—lower your taxable wage baseline. Post-tax deductions, such as court-ordered child support or wage garnishments, do not alter your taxable wage base at all. Reversing these categories in your calculations creates inaccurate tax projections and produces a misleading estimate of your net cash flow.
Miscounting Pay Period Frequencies
Salaried workers frequently miscalculate their regular gross earnings by assuming pay schedules follow calendar months. Dividing an annual salary by 12 months produces an inaccurate figure if an employer actually operates on a bi-weekly schedule consisting of 26 pay cycles per year, or a weekly schedule containing 52 cycles. Using the wrong denominator skews every subsequent deduction and tax calculation.
Overlooking Overtime, Bonuses, and Variable Wages
When projecting annual or monthly earnings, employees sometimes attempt to smooth irregular income—such as performance bonuses, variable commissions, or overtime pay—evenly across all paychecks. In reality, modern payroll calculates withholdings per pay period. Variable earnings must be assessed in the specific cycle they are paid, as sudden increases in gross earnings can shift that single check into a higher withholding bracket.
Forgetting to Update Withholding Assumptions
Your paycheck is never set in stone. Major life events, salary revisions, changes in benefit coverage, or shifts in family circumstances directly influence your tax liabilities. Relying on outdated withholding elections without revisiting the IRS tax withholding calculator can cause cash shortages on payday or lead to unexpected liabilities when filing your annual tax return.
Putting Your Take-Home Pay to Work in Your Household Budget
Accurately determining your net earnings is only the first step; the ultimate value of knowing your take-home pay lies in how you allocate it. Net pay represents your absolute cash ceiling, defining the realistic parameters within which your household must operate.
When mapping out your monthly budget, always allocate your net earnings to core living obligations before funding non-essential categories. Non-negotiable costs must take precedence over every other category:
- Housing: Fixed rent or mortgage payments that secure your home.
- Utilities: Essential electricity, heating, water, and fundamental communications services.
- Food costs: Essential groceries and household provisions required for daily nutrition.
- Critical necessities: Basic healthcare, transportation to work, and immediate family needs.
Once essential survival expenses are fully funded, secondary financial objectives can be addressed. These include building dedicated emergency cash reserves, funding long-term savings buffers, and systematically paying down debt. Treating savings and emergency preparedness as high-priority allocations prevents unexpected expenses from turning into financial emergencies.
Only after core living costs and critical savings goals are satisfied should you direct remaining funds toward discretionary lifestyle spending. Enjoying entertainment, dining out, and luxury splurges from a carefully identified surplus allows you to enjoy your hard-earned money without guilt, stress, or the fear of running short before your next payday.
Frequently asked questions
What is the difference between gross pay and take-home pay?
Gross pay is the total amount of money you earn from your employer before any deductions or withholdings are processed. Take-home pay, or net pay, is the actual dollar amount deposited into your bank account after all pre-tax deductions, statutory taxes, and post-tax withholdings have been removed.
How do pre-tax deductions help save money on taxes?
Pre-tax deductions, such as employer-sponsored health insurance premiums, flexible spending accounts (FSAs), and retirement contributions, are subtracted directly from your gross pay before income taxes are computed. This lowers your taxable income baseline, meaning statutory taxes are assessed on a smaller dollar amount.
How many pay periods are in a typical bi-weekly pay schedule?
A standard bi-weekly pay schedule consists of 26 pay periods per calendar year. If you are paid weekly, your salary is distributed across 52 pay periods. Dividing your annual salary by 12 is only appropriate if your organization pays employees on a strictly monthly schedule.
Are child support and wage garnishments pre-tax or post-tax deductions?
Child support payments and wage garnishments are classified as post-tax deductions. They do not reduce your taxable wage base and are subtracted directly from your earnings only after all required statutory taxes have been withheld.
How can I estimate the exact amount of taxes withheld from my paycheck?
Because withholding amounts depend heavily on your earnings level and tax filing status, you should utilize the official IRS tax withholding calculator or consult a qualified tax professional to accurately determine your per-paycheck tax withholdings.
The Bottom Line
Your gross salary serves as an important benchmark for career progress, but your take-home pay dictates how you navigate day-to-day life. By understanding the multi-step journey from gross compensation through pre-tax deductions, statutory tax withholdings, and post-tax subtractions, you eliminate guesswork from your personal finances.
Whenever your hourly workload shifts, your employer adjusts compensation, or you update your voluntary benefit selections, take the time to run through these payroll steps again. Maintaining an accurate, clear view of your actual net cash flow ensures you make well-informed financial decisions that protect your household and foster long-term financial independence.