How To Set Clear Financial Goals And Move Towards Them
Feeling like you are running endlessly on a financial hamster wheel is an exhausting, common reality for millions of hardworking adults. Despite earning a consistent income and putting in long hours, many households watch their paychecks vanish into everyday expenses, unnoticed conveniences, and recurring leaks without ever making meaningful progress toward homeownership, debt reduction, or cash reserves.
The underlying issue is rarely a lack of personal work ethic; rather, it is the absence of a defined target and an actionable, daily system to reach it. When money enters a bank account without a designated assignment, it naturally dissipates. Transforming personal finances requires moving from reactive spending to proactive direction through structured goal setting, honest tracking, and decisive daily action.
Key takeaways
- Vague aspirations must be replaced with exact, dated numbers, such as budgeting $416 per month over twelve months to reach a $5,000 target.
- Displaying written targets and visual boards in high-traffic home areas keeps long-term priorities ahead of immediate spending impulses.
- A workable financial plan requires absolute honesty about every single transaction, without rounding up or ignoring minor leaks.
- Visualizing targets is useless without direct physical action, such as securing extra work, making deliveries, or establishing dedicated savings deposits.
- Logging every cent daily prevents spending blind spots from derailing progress before pay periods end.
The Mechanics of Purposeful Money Management
Financial goal setting provides the foundation for personal economic stability. Without structured targets, money flows through a household in a purely reactive manner. Bills arrive, impulse purchases happen, minor conveniences accumulate, and by the end of the pay period, you are left wondering where your earnings went. Setting concrete targets shifts money management into an active, deliberate system where every dollar is assigned a specific job before it is spent.
Human psychology responds powerfully to written and visual cues. When financial ambitions remain trapped inside your head, they compete directly with daily fatigue, stress, and spontaneous spending impulses. Translating an ambition into a physical record anchors your intentions in physical reality. Each financial choice becomes a direct, conscious vote either in support of or against your stated targets.
Furthermore, achieving any long-term ambition requires a functional feedback loop. You establish an initial expectation, execute the necessary physical steps, record your real-world outcomes, and honestly evaluate the variance between your plan and your actions. This continuous cycle of planning, taking action, and reviewing performance creates self-reinforcing momentum over weeks, months, and years.
Action bridges the gap between the plans posted on your refrigerator and the tangible reality of your bank balance.
Six Core Strategies for Setting and Reaching Financial Goals
Breaking out of financial inertia requires practical routines that replace confusion with clarity. Implementing these six foundational strategies provides the framework needed to define your targets and systematically move toward them.
1. Write Down Your Goals in Black and White
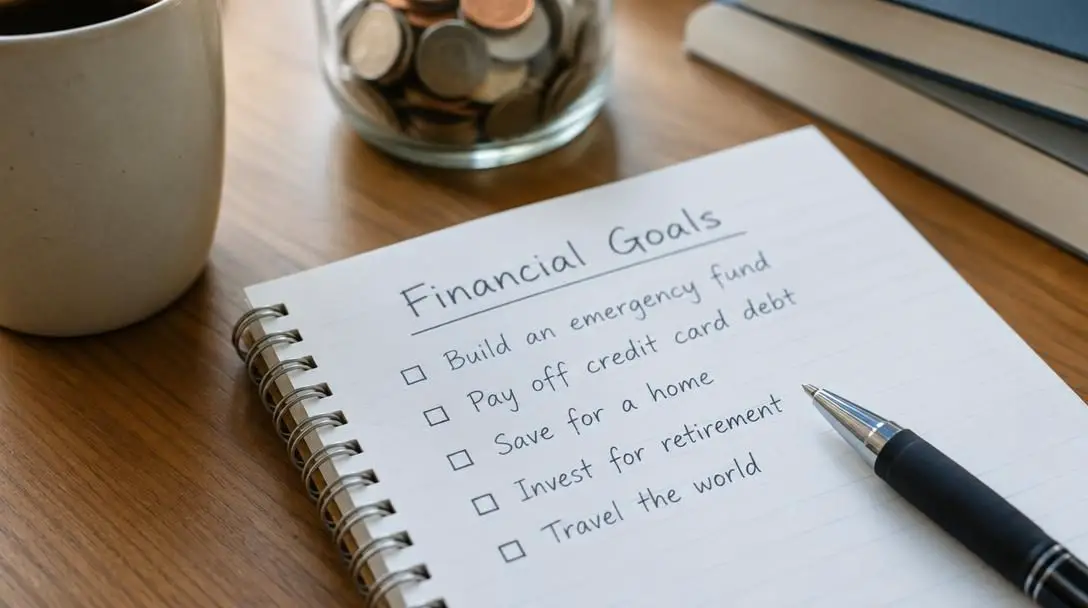
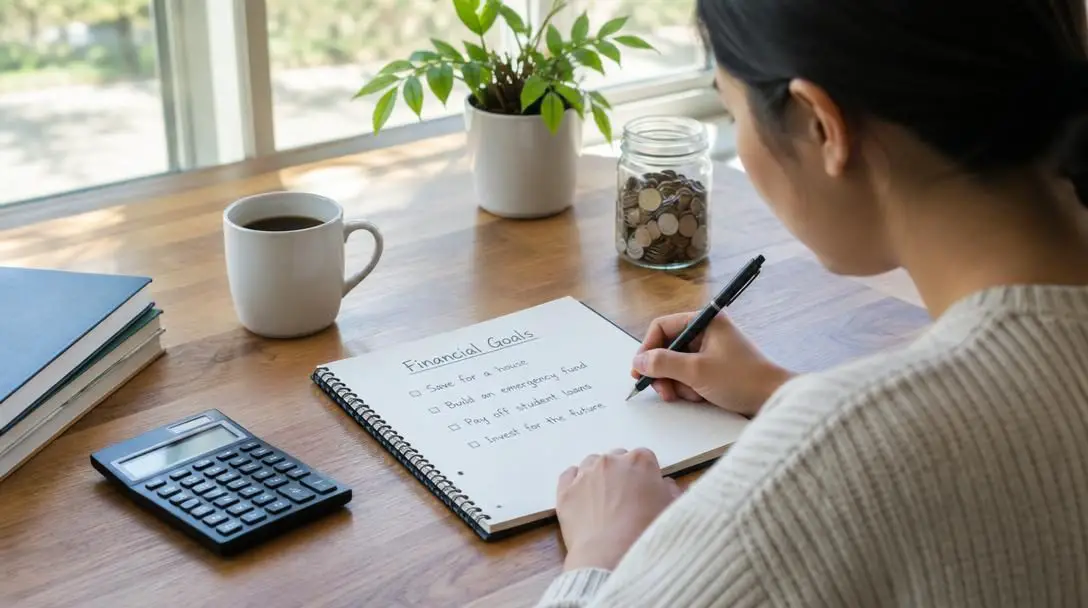
The first vital step in taking control of your financial future is getting a dedicated notebook and writing down your objectives. Transferring ideas from your thoughts onto physical paper solidifies them, transforming abstract wishes into concrete commitments that you can review and evaluate repeatedly. Putting your targets on paper makes them feel tangible and genuinely achievable.
Whenever you write down a target, record the exact current date next to it. Documenting your starting date creates a permanent timeline of your personal growth, allowing you to reflect later and see precisely how long it took to achieve each milestone. Once written, do not hide the paper away inside a drawer. Post it in a prominent, high-traffic location, such as on your refrigerator door or a main bulletin board, so you encounter an unavoidable reminder of your targets every single day.
2. Make Goals Specific and Measurable
Vague ambitions do not generate the focus or urgency needed to alter daily spending patterns. Declaring that you want to save more money or get better with your finances provides no actionable parameters. To build genuine traction, every target must be defined with unambiguous mathematical detail.
Instead of setting a broad goal such as saving $5,000, convert that objective into an operational monthly assignment: saving exactly $416 a month for 12 months. This shift demystifies a large, intimidating sum by turning it into a manageable, recurring commitment. Clear numerical metrics allow you to organize your spending, evaluate whether you are on schedule, and make necessary mid-course adjustments.
3. Assemble a Daily Vision Board
While written figures establish an operational roadmap, pictures tap into the motivational power of visualization. A vision board serves as a physical, pictorial display of what you intend to accomplish with your money. Many people are surprised by how quickly their financial ambitions turn into reality once they implement a dedicated visual board in their home environment.
You can create a vision board by cutting photos out of magazines or searching online and printing high-quality representations of your specific ambitions. If your primary aim is to purchase your own home, locate and display pictures of the exact style and type of house you want to buy. Hang this board in a high-visibility spot where you will view it every morning and evening, keeping your ultimate destination front of mind when faced with decisions between instant gratification and your broader vision.
4. Execute Tangible, Direct Actions
Writing down targets and arranging pictures on a board are valuable preparatory exercises, but visualization alone will never alter a bank balance. You cannot simply sit back and wait to win the lottery to resolve economic challenges. Real progress requires active, sustained, and uncomfortable physical effort.
Depending on your current circumstances and targets, direct action may require expanding your income or restricting capital outflows. Practical ways to take immediate action include:
- Securing a second job to boost incoming cash flow.
- Driving for a ride-share company during spare evening or weekend hours.
- Completing deliveries to bring in supplementary income.
- Opening a separate, dedicated savings account and scheduling recurring, non-negotiable deposits into it.
5. Maintain Radical Self-Honesty
A functional financial plan cannot operate on false premises, fudged numbers, or convenient omissions. Never attempt to deceive yourself regarding your financial habits or progress. If you deposit only $18 into your savings account during a given week, you must record that exact figure rather than telling yourself you put away $20. Accuracy matters, regardless of how minor the difference may seem.
Gaining complete command of your economic life requires examining your current circumstances without excuses. Look directly in the mirror and make a firm commitment to absolute honesty about your money. Take an unsparing inventory of your spending: determine if you are blowing funds on non-essential purchases, and identify whether you are maintaining expensive personal habits that quietly siphon hundreds of dollars out of your monthly budget.
6. Track Every Penny on a Daily Basis
Reaching the end of a pay period and wondering where all your earnings disappeared is the direct result of passive tracking. Letting even twenty-four hours pass without recording your transactions creates blind spots that derail budgets and conceal wasteful spending patterns.
You can track transactions using any method that fits your personal workflow, whether that means dedicated accounting software, mobile applications, or a pocket-sized paper ledger. The specific format is far less critical than strict consistency. Adopt the mindset of a miser when accounting for your capital, treating every single cent with importance and recording every transaction that leaves your possession.
Comparing Goal-Setting Approaches
Understanding the distinction between vague financial wishes and structured targets highlights why traditional resolutions so frequently fall apart.
| Focus Area | Vague Approach | Structured Strategy | Operational Outcome |
|---|---|---|---|
| Savings Ambition | Save $5,000 eventually | Deposit $416 a month for 12 months | Clear monthly benchmark with zero ambiguity |
| Income Growth | Hope to win the lottery | Work a second job, drive ride-share, or deliver | Direct, predictable control over incoming cash flow |
| Record Keeping | Rough estimates at month's end | Daily logging of every cent in an app or notebook | Immediate identification of non-essential leaks |
| Accountability | Rounding up an $18 deposit to $20 | Recording the exact $18 deposit truthfully | Accurate financial records and total self-honesty |
A Step-by-Step Implementation Guide
Shifting from financial stagnation into an active, disciplined routine works best when executed through an orderly sequence of actions. Follow this implementation plan to establish your foundation.
- Assemble your recording tools: Procure a dedicated notebook, a reliable pen, and your preferred transaction tracking tool, whether that is specialized accounting software, a smartphone application, or a simple paper register.
- Draft and date your initial targets: In your notebook, record your primary financial goals in bold, plain language. Write the current date clearly at the top of the sheet, and break every objective into an exact figure and schedule, such as saving $416 monthly across a 12-month period.
- Display your written plan publicly: Tear the completed goal sheet from your notebook or write a clean duplicate, and mount it in a prominent household space, such as your refrigerator door or a living area bulletin board.
- Construct your physical vision board: Source photographs from print publications or online databases that mirror your specific dreams, such as a picture of the exact style of home you intend to purchase. Fasten them to a display board and hang it where you will view it daily.
- Execute an unsparing spending audit: Review your recent accounts with complete transparency. Identify costly habits and non-essential expenditures that drain hundreds of dollars from your budget each month, making sure you record accurate figures without rounding down leaks or inflating savings.
- Initiate daily transaction tracking: Log every single expenditure each day as it occurs. Account for every cent that leaves your hands, ensuring no cash or digital payment goes unrecorded.
- Launch direct earning and saving measures: Open a dedicated savings account to receive non-negotiable deposits, or generate supplementary income by picking up a second job, transporting passengers on a ride-share platform, or completing deliveries during open hours.
Common Financial Goal Pitfalls to Avoid
When embarking on a new financial path, enthusiasm can easily be derailed by common behavioral traps. Being aware of these missteps helps protect your progress over the long haul.
- Relying on vague, unquantified targets: Hoping for general economic improvement or aiming to save more provides no practical standard against which to measure daily choices. Convert all ambitions into explicit numbers and deadlines.
- Compromising self-honesty: Writing down inaccurate numbers or pretending that a missing couple of dollars is irrelevant creates compounding accounting errors and weakens your discipline.
- Treating visualization as a replacement for labor: Hanging a vision board without executing direct physical actions—such as taking extra shifts, driving ride-share, or funding a separate savings account—leaves your ambitions entirely stranded on paper.
- Postponing expense logging: Attempting to reconstruct spending at the end of the week or pay period guarantees that incidental cash purchases and minor conveniences will be omitted, causing expenses to slip by unnoticed.
Frequently asked questions
Why must I write the current date next to my financial goals?
Recording the starting date next to each target creates a historical baseline for your financial journey. It holds you accountable to a concrete timeline and allows you to look back in the future to see exactly how long it took to achieve each milestone, providing concrete proof of personal growth.
How does breaking a large target into monthly amounts help?
Large figures, such as targeting $5,000, can feel overwhelming and lead to procrastination. Breaking that figure down into $416 a month for 12 months transforms an intimidating lump sum into a manageable, recurring assignment that fits cleanly into your monthly spending plan.
What should I do if an audit reveals costly spending habits?
Confront the reality without making excuses or hiding the numbers. Identify exactly how many hundreds of dollars those habits consume each month, and deliberately redirect those funds toward your non-negotiable monthly savings deposits or debt reduction targets.
Is a smartphone app better than a paper notebook for daily tracking?
Neither tool is inherently superior; what matters is consistent, daily execution. Some individuals achieve better results using mobile apps or software, while others stay more engaged using a physical piece of paper. The only requirement is that every single penny spent is recorded without exception.
Why is visualization alone insufficient to achieve financial freedom?
Vision boards and written lists are cognitive reminders that maintain focus and combat impulse spending, but they lack the operational power to deposit cash or pay down account balances. Progress requires real, physical action, such as working a second job, completing deliveries, driving for ride-share, or cutting non-essential purchases.
The Bottom Line
Escaping the exhausting hamster wheel of paycheck-to-paycheck living does not hinge on luck, chance, or winning the lottery. It requires replacing vague hopes with an uncompromising system built on dated targets, visual reminders, complete personal honesty, and relentless daily tracking.
Every dollar you earn should serve a defined purpose toward your broader vision, whether that entails purchasing a home, building a secure cash cushion, or eliminating debt. By breaking broad figures down into specific monthly requirements, maintaining accurate records down to the cent, and generating additional income through active work, you construct the momentum needed to reach your targets. Pick up a notebook, record your starting date, and begin tracking your path today.