Top 5 Tips To Manage Your Finances Better
Money management remains a significant hurdle for millions of Americans today. This challenge is felt most acutely by households living paycheck-to-paycheck, where every dollar earned is immediately absorbed by mandatory living costs. In such circumstances, even minor miscalculations or unexpected bills can disrupt household stability. However, whether an individual needs a complete financial overhaul or simply wants to free up extra cash, positive transformation is entirely achievable through consistent, disciplined habits.
Personal finance is not merely determined by how much income an individual generates; it is fundamentally governed by how that money is directed, retained, and allocated over time. Without deliberate oversight, funds slip away through unmonitored daily purchases, unnoticed recurring subscriptions, and compounding interest charges. Gaining control requires transitioning from a reactive mindset—responding to bills only as they arrive—to a proactive posture where money is managed with clarity and purpose.
Key takeaways
- Tracking every transaction eliminates unconscious spending and reveals immediate opportunities to cut recurring non-essential expenses.
- A realistic budget calculates firm monthly commitments first to accurately establish true disposable income.
- Targeting high-interest balances or using a debt consolidation loan minimizes interest charges and accelerates the path to debt relief.
- Paying bills punctually protects credit standing and prevents routine obligations from escalating through late fees and penalty rates.
- Saving cash for major purchases eliminates interest costs, preserves peace of mind, and curbs the financial hazards of instant gratification.
The five core mechanisms of personal financial management
Sound personal financial management operates on a straightforward mathematical and behavioral framework: balancing cash inflows against outflows while systematically reducing obligations and preparing for upcoming costs. Navigating this framework requires coordinating five interdependent mechanisms.
The first mechanism is total visibility. You cannot effectively manage what you do not actively monitor. Documenting every transaction removes guesswork and exposes habitual spending leaks that deplete cash reserves.
The second mechanism is structural planning through budgeting. A budget acts as an operational roadmap, identifying non-negotiable living expenses—such as mortgage or rent payments and basic utilities—and contrasting them with net earnings to define actual disposable income.
The third mechanism is debt mitigation and liability control. Debt carries carrying costs in the form of interest rates, siphoning future earnings away to satisfy past spending. Restructuring or methodically eliminating liabilities restores cash flow.
The fourth mechanism is procedural reliability. Paying every bill on schedule and in full shields your credit profile from damage while eliminating costly penalties and sudden interest rate spikes.
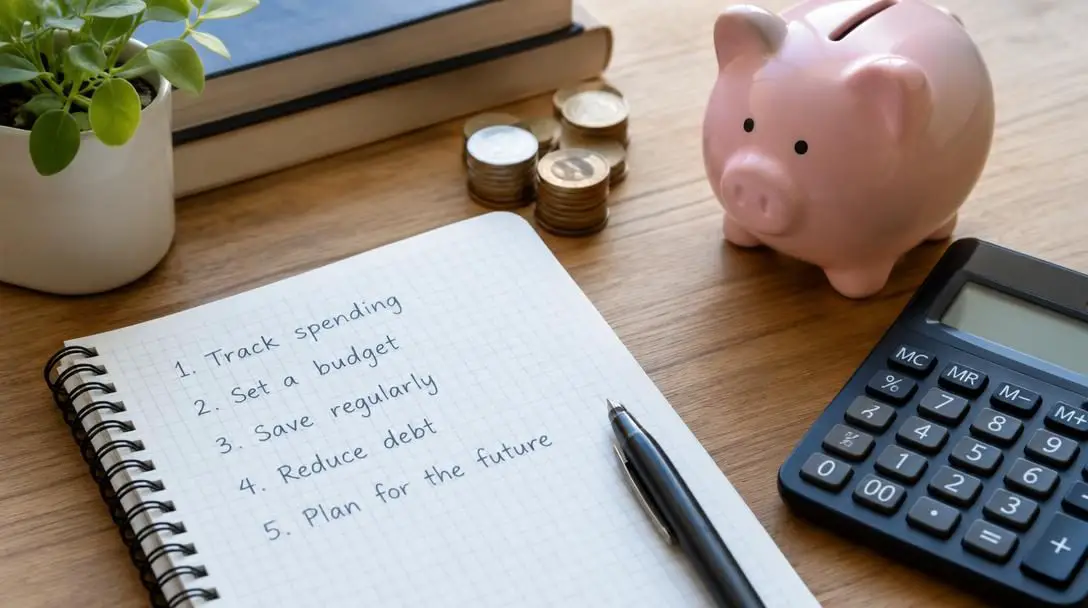
The fifth mechanism is patience and capital accumulation. Choosing to accumulate cash for larger outlays rather than relying on credit cards prevents high interest charges and insulates the household against runaway debt.
At a glance: Core strategies to manage personal finances
| Strategy | Primary Focus | Immediate Benefit | Preventable Risk |
|---|---|---|---|
| Track Spending | Transaction logging and expense audits | Uncovers unconscious daily spending leaks | Cash drain from unused subscriptions |
| Create a Monthly Budget | Firm expense calculation vs. net income | Defines precise pool of disposable income | Budgetary shortfalls and overspending |
| Pay Down Debt | High-interest balances and consolidation | Lowers carrying costs of borrowing | Compounding interest and persistent balances |
| Pay Bills On-Time | Calendar tracking and scheduled payments | Protects credit standing and saves cash | Costly late fees and penalty interest rates |
| Save for Large Purchases | Cash accumulation before buying | Ensures purchase stays at true retail cost | Debt accumulation from instant gratification |
Top 5 tips to manage your finances better
Personal finance is fundamentally about how income is directed, retained, and allocated rather than simply how much money you earn.
Track your spending
Proactive expense tracking forms the foundation of all financial improvement. When spending goes unmonitored, modest daily purchases quietly compound into a massive portion of monthly earnings. Gaining visibility requires examining every transaction across bank accounts, credit card statements, and cash withdrawals. Focus closely on discretionary expenses that can be trimmed, such as entertainment memberships and streaming services that persist long after their initial appeal has waned. Documenting these outflows reveals where money is actually going and frees up immediate cash for higher priorities.
Create a monthly budget
A successful budget must be as realistic as it is accurate. An overly restrictive plan that permits no flexibility will quickly collapse under frustration, while an inaccurate budget leaves households vulnerable to unexpected shortfalls. Begin by compiling all firm expenses—mandatory commitments like rent or mortgage, utility bills, and basic living necessities. Calculating these non-negotiable costs reveals the precise baseline required to keep the household functioning. Subtracting that figure from total net income isolates genuine disposable income, enabling clear, informed decisions about savings and discretionary spending.
Pay down debt
Managing debt requires strategic intentionality rather than haphazard, unstructured payments across multiple balances. If you carry several credit card balances, focus surplus funds on the account carrying the highest interest rate first. Eliminating the costliest debt minimizes the total amount lost to interest over time. Additionally, consider exploring a debt consolidation loan. Combining various credit card balances into a single loan replaces scattered due dates with one predictable monthly payment, frequently securing a smaller interest rate that accelerates overall debt reduction.
Pay bills on-time
Maintaining financial momentum requires paying all recurring bills on time and in full each month. Late payments produce two severe consequences: they damage your credit profile and trigger avoidable financial penalties. Allowing a deadline to slip transforms an ordinary $200 obligation into a $250 bill through late fees and sudden penalty rate hikes. Maintaining a comprehensive chart of all payment deadlines and outstanding balances ensures no expense is overlooked, protecting hard-earned income from administrative penalties.
Save for large purchases
While credit cards provide immediate gratification, saving cash in advance for major purchases delivers decisive financial advantages. Buying an item outright with accumulated savings eliminates compounding interest charges, which often make large credit purchases far more expensive than their initial price tags suggest. Furthermore, paying with cash completely removes the risk of late fees or elevated penalty interest rates caused by future missed card payments. Exercising patience preserves personal peace of mind and keeps major acquisitions within their true retail cost.
Step-by-step implementation guide
Translating these broad principles into permanent daily practices requires an organized, sequential approach. Follow these structured steps to put your personal financial system into operation:
- Gather all recent financial documentation, including bank account statements, credit card bills, utility invoices, and recent pay stubs.
- Audit every line item from the prior month to record every expense and classify where all income was spent.
- Cancel unnecessary discretionary subscriptions and underused recurring memberships immediately to recover cash flow.
- Draft a formal monthly budget by listing net earnings alongside non-negotiable firm expenses like rent, mortgage, and utilities.
- Subtract firm expenses from total income to determine your exact monthly pool of disposable income.
- Build a central debt tracking chart listing balances, minimum payments, and interest rates for every outstanding credit line or loan.
- Construct an organized monthly calendar displaying every bill deadline to ensure timely payment execution.
- Establish a strategic payoff plan targeting the card with the highest interest rate, or research debt consolidation loan terms to combine accounts.
- Open a designated cash savings fund tailored to an upcoming major purchase rather than charging it to credit cards.
- Conduct a weekly financial review to verify transaction records, track budget compliance, and confirm upcoming bill payments.
Common mistakes to avoid
Many individuals encounter avoidable pitfalls when attempting to regain control of their money. Remaining alert to these missteps helps preserve long-term progress:
- Neglecting to log small daily purchases, leaving an incomplete record of actual cash flow patterns.
- Designing an excessively rigid budget that ignores routine personal comfort, leading to early frustration and plan abandonment.
- Underestimating fluctuating firm costs like seasonal utility bills, resulting in skewed calculations of disposable income.
- Distributing surplus debt payments evenly across all accounts instead of targeting high-interest balances systematically.
- Relying on mental reminders to pay bills instead of maintaining a written schedule of balances and due dates.
- Allowing missed due dates to inflate standard bills with preventable late penalties and penalty borrowing rates.
- Giving in to instant gratification by financing large consumer purchases without a clear repayment strategy.
- Discounting the cumulative financial impact of interest charges over the lifespan of credit purchases.
- Abandoning financial management efforts prematurely because organizing account paperwork initially feels time-consuming.
Long-term outlook: What to consider next
Once you have established the fundamentals of tracking expenses, maintaining an accurate budget, tackling high-interest debt, paying bills punctually, and saving cash for significant purchases, focus on sustaining your momentum.
First, evaluate how to reallocate funds as liabilities decrease. When high-interest credit cards are paid off or merged into a debt consolidation loan with a single monthly fee, significant amounts of cash formerly lost to interest charges are freed. Decide deliberately whether to route this reclaimed disposable income toward savings for upcoming large purchases or toward other long-term personal goals.
Second, ensure that your tracking habits and payment schedules become permanent operational tools. Financial management is an evolving practice rather than a one-time project. As seasonal utility expenses shift, housing payments change, or household income increases, update your monthly budget to keep it accurate and grounded in reality.
Finally, recognize the psychological advantages of sustained financial control. Moving away from the chronic anxiety of living paycheck-to-paycheck and eliminating the threat of penalty fees brings lasting stability. Committing to modest, regular oversight yields enduring security for years to come.
Frequently asked questions
Why is personal money management challenging for paycheck-to-paycheck households?
When living paycheck-to-paycheck, every dollar earned is immediately committed to urgent living expenses. In this vulnerable position, unexpected expenses or minor calculation errors can instantly destabilize household finances, leaving little margin for error without deliberate planning.
How do firm expenses differ from disposable income in a budget?
Firm expenses represent non-negotiable living costs required to keep a household functioning, such as rent, mortgage payments, and basic utilities. Disposable income is the remaining balance of net earnings once all firm obligations have been subtracted, which can then be purposefully allocated to savings, debt payoff, or discretionary spending.
What makes targeting high-interest debt the most effective payoff strategy?
Carrying high-interest balances drains future cash flow through compounding borrowing costs. By directing extra payments toward the highest interest rate accounts first, you eliminate the most expensive debt fastest, significantly reducing the overall amount paid in interest over time.
How does a debt consolidation loan assist with credit card debt?
A debt consolidation loan combines multiple credit card balances into a single monthly fee. This simplifies finances by replacing scattered payment deadlines with one due date and often secures a smaller interest rate, speeding up the journey out of debt.
What are the hidden costs of missing a bill payment deadline?
Missing a payment deadline damages your credit standing and triggers direct monetary penalties. A missed deadline can turn an ordinary $200 bill into a $250 obligation through late fees and can provoke penalty interest rate hikes that increase borrowing costs across future billing cycles.
Why is saving cash for large purchases better than using a credit card?
Saving cash prevents buyers from falling into the trap of instant gratification. Purchasing items outright avoids expensive interest charges that inflate the true cost of goods, eliminates the risk of missing card payments, and guards against costly penalty fees and punitive interest rates.
The bottom line
Achieving lasting financial stability does not require an extraordinary income; it requires disciplined, intentional management of the income you have. By tracking daily spending, establishing an accurate monthly budget, eliminating high-interest liabilities, paying obligations promptly, and saving cash for significant purchases, you replace reactive financial stress with structured control. These consistent, straightforward actions insulate your household against unexpected disruptions, eliminate needless fees, and establish a dependable foundation for lasting peace of mind.